
What do HOA fees cover? A plain-language guide to where your money goes.
That line on your statement, or on the listing for a home you love, has a simple answer: your fee pays for the things you and your neighbors share. Here is what it covers, what makes it higher or lower, and how to see your own community’s numbers.
The short version
HOA fees pay for what homeowners share — common areas, amenities, insurance on shared property, reserves for future repairs, and the work of running the community. What you pay depends on what your community maintains, and you should be able to see where every dollar goes.
You just saw the number — on a statement, on a listing, or in a budget notice that landed in the mail this fall — and the obvious question is: what do HOA fees cover? The short answer is the one above. Your fee pays for the parts of the community everyone shares, from the entrance and the pool to the insurance on shared buildings and the savings that pay for the next roof. When people ask what does HOA cover, that is the honest, unglamorous list.
Nobody enjoys a bill they can’t itemize, so this guide does the itemizing. We’ll walk through what your fee pays for, what it usually doesn’t, what makes one community’s fee higher than another’s, how fees get set and when they can change, and — the part most guides skip — exactly where to look to see your own community’s numbers.
What do HOA fees cover?
HOA fees cover the costs of owning and maintaining the parts of the community everyone shares. Put another way, what does an HOA pay for? Boiled down, your fee pays for five things:
- Common area maintenance — landscaping, entrances, ponds, and shared grounds
- Amenities and shared utilities — pools, clubhouses, and the power and water that keep common spaces running
- Insurance on shared property and the association’s liability
- Reserves — savings set aside for big future repairs
- Management and administration — the work of running the community
Common area maintenance and landscaping
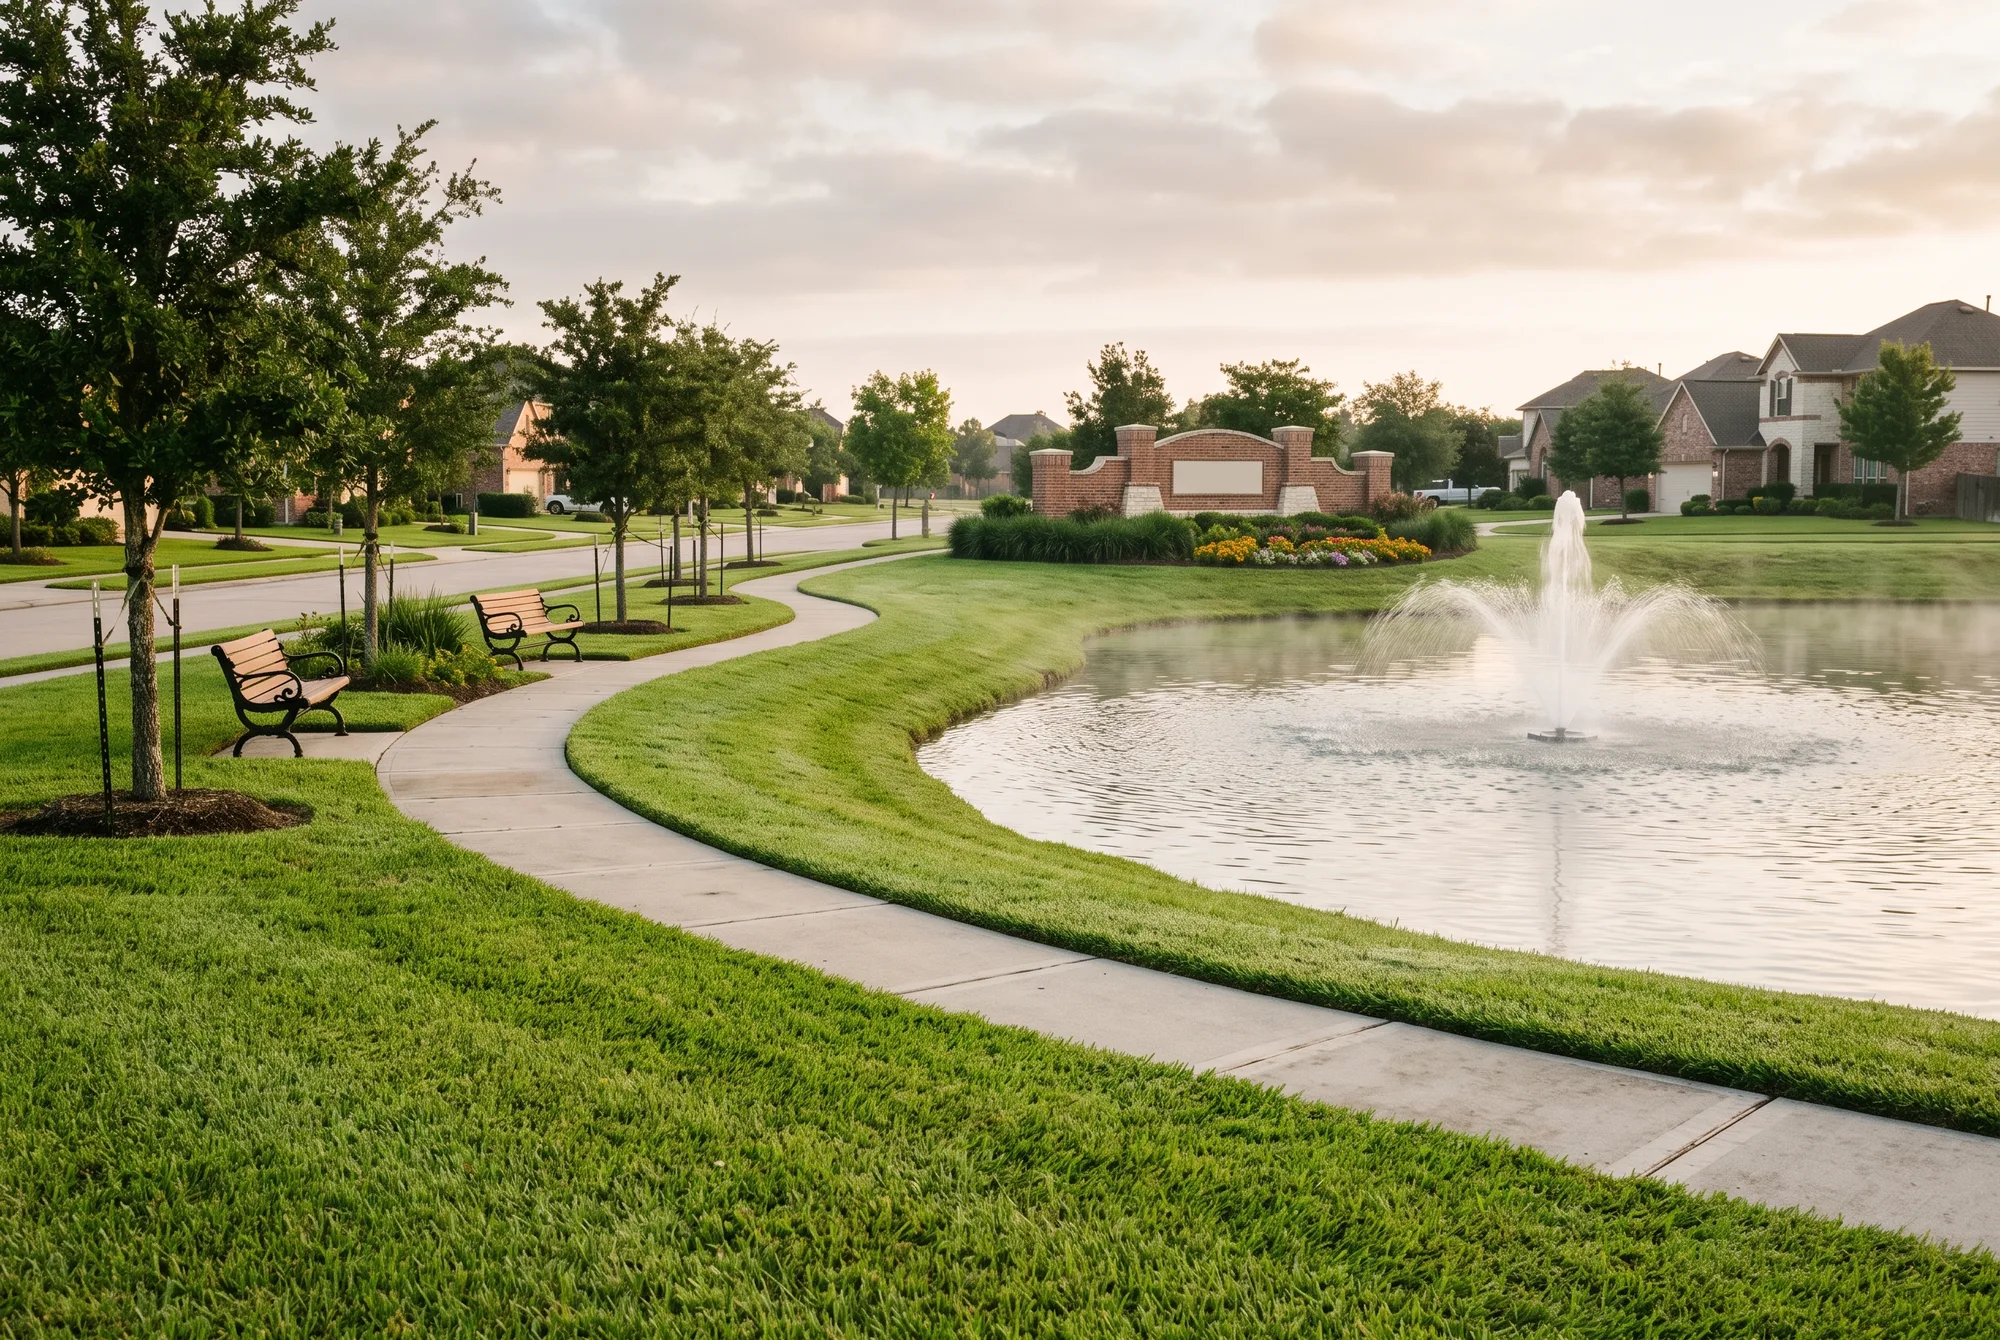
This is the part you see every day: mowing and landscaping at the entrance and along the medians, the pond and its fountain, sidewalks and streetlights, and private roads where the community owns them. It’s the single most visible thing your fee buys. A manager bids and oversees the vendors who do this work — soliciting competitive bids and holding contractors to them is one of the everyday ways fees are kept in check rather than left to climb.
Amenities and shared utilities
Pools, clubhouses, fitness rooms, and playgrounds are funded here, along with the utilities that keep shared spaces running: common-area electricity for streetlights and the pool, and water for irrigation. Do HOA fees include utilities for your own home? Usually not — but it depends on the community. Some associations fold a service like water or trash into the fee for every home, while most leave your household utilities to you. Your budget spells out which.
Insurance on shared property
Part of your fee buys the association’s master insurance policy, which covers shared property and the association’s liability. It does not replace your own homeowner’s policy — the two cover different things. In the Gulf South, wind and flood exposure make insurance a bigger slice of the budget than it is in much of the country, which is why CMGT keeps a dedicated Insurance & Reserve department on it. Our guide to the HOA master insurance policy covers where the association’s coverage ends and yours begins; the National Flood Insurance Program explains why flood coverage is almost always separate.
Reserves: savings for future repairs
Part of every fee is set aside for big, predictable costs that are years away — a new roof, resurfaced roads, a repainted clubhouse, pool equipment, fencing. This is the reserve fund, and it’s the quiet reason a well-run community rarely gets hit with a surprise bill. A funded reserve is what lets the association replace the roof when it wears out instead of passing the hat. An HOA reserve study sets the target so the savings keep pace with what’s wearing out.
Management and administration
This covers the work of actually running the community: the management fee, accounting and annual tax preparation, legal costs, meetings and records, and the homeowner communication that keeps everyone informed. It’s the least visible line and the one that keeps the other four organized. You can see how the pieces fit together in our overview of HOA financial management.
What HOA fees usually don't cover
HOA fees generally don’t cover anything inside your home, your own homeowner’s insurance, or repairs to property you own individually — but where exactly the line falls depends on your community. Take the roof: does an HOA cover roof repairs? In most single-family communities the homeowner owns and maintains the roof, while in some townhome or condominium communities the association may. The only reliable answer is in your governing documents, which define exactly what the association maintains and what it doesn’t.
| Usually covered by the association | Usually your responsibility |
|---|---|
| Common areas, entrances, and shared landscaping | The inside of your home and its systems |
| Shared amenities like the pool and clubhouse | Your own homeowner’s (or HO-6) insurance |
| Master insurance on shared property | Your yard and anything you own individually |
| Reserves for shared components | Your roof, in most single-family communities |
When in doubt, the governing documents decide, not the general rule. If the split isn’t clear, ask your manager to point you to the section that spells out what the association maintains.
How much are HOA fees? It depends on what your community maintains
There’s no meaningful “average” HOA fee, and any number you see online won’t apply to your community. The fee is set by what each community has to maintain — more to maintain usually means a higher fee that covers more. So instead of chasing an average, look at what moves the number:
- Amenities. A pool, clubhouse, and gym cost more to run than an entrance sign and a pond.
- How much the association maintains. Common areas only is very different from a community that also maintains exteriors, roofs, or every home’s landscaping.
- Community type. Single-family, townhome, and condominium communities share different amounts of property, so their fees are built differently.
- Age. Older roads, roofs, and amenities need more upkeep and bigger reserve contributions.
- Reserve health. A community that’s catching up on underfunded reserves pays more now than one that’s stayed ahead.
- Insurance. Coastal wind and flood exposure pushes premiums up here, and that flows straight into the fee.
- Size. The same costs split across more homes mean a lower share for each.
When you’re comparing two communities, compare what each fee covers, not just the number. A lower fee that leaves the roof to you, or skips reserves, can cost more in the end.
Why are HOA fees so high?
When fees feel high, it’s usually because the community’s costs have gone up — and sometimes because some homeowners aren’t paying. Nobody likes a bigger bill, so here’s the honest breakdown of what’s usually behind it:
- Insurance. In the Gulf South, wind and flood coverage is one of the fastest-rising costs a community faces.
- Vendor and material costs. Landscaping, pool service, and repairs all cost more than they did a few years ago.
- Aging components. Roads, roofs, and amenities need more attention as they get older.
- Reserves catching up. A community that underfunded its reserve fund in past years has to build it back, and that shows up in the fee.
- Delinquency. When some homeowners don’t pay, the cost lands on the ones who do. Our guide to HOA collections and delinquency explains how a good process keeps that from spreading.
One more distinction worth drawing: your regular fee funds the yearly budget, while a special assessment is a separate, one-time charge for something the budget and reserves didn’t cover. A well-funded reserve is the best protection against ever seeing one. A higher fee that funds reserves is often cheaper than a low fee and a surprise assessment later.
How are HOA fees determined, and when can they go up?
HOA fees come from the community’s annual budget. Each year the board estimates what it will cost to run and maintain the community — every category above, including the reserve contribution — and divides that total among homeowners according to the governing documents. That’s how HOA fees are determined: not by a rule of thumb, but by what the community actually plans to spend. Our HOA budget template shows how the pieces add up.
Can an HOA raise fees? Usually yes, through that same budget process, since costs rarely hold still. But the limits — how much the board can raise fees on its own, how much notice homeowners get, and whether a vote is required above a certain amount — depend on your governing documents and your state’s law. We manage communities; we don’t practice law, so we won’t tell you what your state requires. For that, find your state’s HOA law guide in our Resources library and, when it matters, check with your association’s attorney.
How to see where your HOA fees go
The best way to see what your fees pay for is to read two documents: your community’s annual budget and its financial statements. Between them, they show exactly where the money goes. You don’t need an accounting background — here’s what to look for.
Three things to look for
- The budget’s major categories. They line up with the five things above — maintenance, amenities, insurance, management, and reserves.
- The reserve contribution line. This is the savings piece. It’s a normal, planned part of the fee, not an extra.
- Actual vs. budget. The financial statements show what was really spent against what was planned, so you can see how close the community is running.
The table below shows how a budget is usually organized, so the categories feel familiar when you open your own.
Example: how an HOA budget is organized. An illustrative example for a single-family community with a pool. Your community’s budget will look different — the line items depend on what your association maintains.
| Budget section | Line item | What it pays for |
|---|---|---|
| Operating — Maintenance | Landscaping and mowing | Common areas, entrances, and medians |
| Pond and drainage upkeep | Keeping shared water features and drainage working | |
| Common-area repairs | Fences, signs, and lighting | |
| Operating — Amenities | Pool service and chemicals | Keeping the pool open and safe |
| Pool furniture and supplies | Chairs, umbrellas, and equipment | |
| Clubhouse cleaning and upkeep | The shared indoor space | |
| Operating — Utilities | Common-area electricity | Streetlights, pool, and the entrance |
| Irrigation water | Watering common-area landscaping | |
| Operating — Insurance | Master property and liability policy | Shared property and the association’s liability |
| Directors & officers coverage | Protecting volunteer board members | |
| Operating — Management & admin | Management fee | Running the community day to day |
| Accounting, tax prep, and legal | Books, filings, and counsel | |
| Postage, printing, and bank fees | Homeowner communications and banking | |
| Reserve contribution | Transfer to reserves | Saving for future repairs and replacements — pool resurfacing, fencing, roads, the entrance monument (set by the reserve study) |
Two parts are worth noticing. The operating budget is this year’s costs; the reserve contribution is savings for later, and it’s a normal line, not an add-on. When your fee changes, compare this year’s budget to last year’s to see which lines actually moved.
What transparency can look like
At CMGT, full monthly financials — the profit-and-loss statement and the balance sheet — go to the entire ownership, not just the board, by the 20th of every month. It’s written into the management agreement, and about 70% of homeowners use the portal to check it. We think seeing the numbers is the whole point.
If CMGT manages your community, your financials are in your portal — sign in through the homeowner login to see your community’s budget and monthly statements. And the annual meeting is the place to ask questions about any line you don’t recognize.
Frequently asked questions about HOA fees
Are HOA fees worth it?
It depends on what your fee covers and how well the community is run. In exchange you get shared amenities, maintained common areas, and a plan that protects property values; the trade-offs are the cost and the rules. The clearest way to judge it is to look at your community’s budget and see where the money goes.
Can an HOA raise fees without a vote?
It depends on your governing documents and state law. Some documents let the board adopt a budget that raises fees without a separate homeowner vote; others cap increases or require a vote above a certain amount. Check your governing documents, and find your state’s HOA law guide in our Resources library.
What’s the difference between HOA dues and a special assessment?
Dues are the regular fee that funds the annual budget; a special assessment is a one-time charge for a cost the budget and reserves didn’t cover. Healthy reserves make a special assessment less likely.
Do HOA fees include utilities?
Usually only the utilities for shared spaces, like electricity for streetlights and the pool or water for irrigation. Some communities also include a service like water or trash for each home. Your budget or your manager can tell you which.
Why did my HOA fees go up this year?
Most increases trace back to higher costs in the new budget, often insurance, vendor pricing, or reserve contributions. Your budget will show which lines changed, and the annual meeting is the place to ask about them.
Your fee pays for what you share
That’s the whole idea: your HOA fee pays for the things you and your neighbors share, it’s set by what your community has to maintain, and you should always be able to see where every dollar goes. When the numbers are open, a fee stops feeling like a mystery bill and starts looking like what it is — a shared plan for a community you own a piece of.
If you’re on a board and your homeowners can’t see where their money goes, that’s worth fixing. It’s the thing we hear the most relief about after a community switches.
This article is general guidance for homeowners and boards, not legal, tax, or financial advice, and it isn’t a description of any specific community’s budget. The sample budget is an illustrative example, not a typical or average one. What your association maintains, and how and when fees can change, are set by your governing documents and your state’s law; confirm the specifics with your association’s attorney.